

 PBOC Aims to Offset Holiday, Quarter-End Liquidity With USD14.9 Billion 14-Day Reverse Repo, Analysts Say
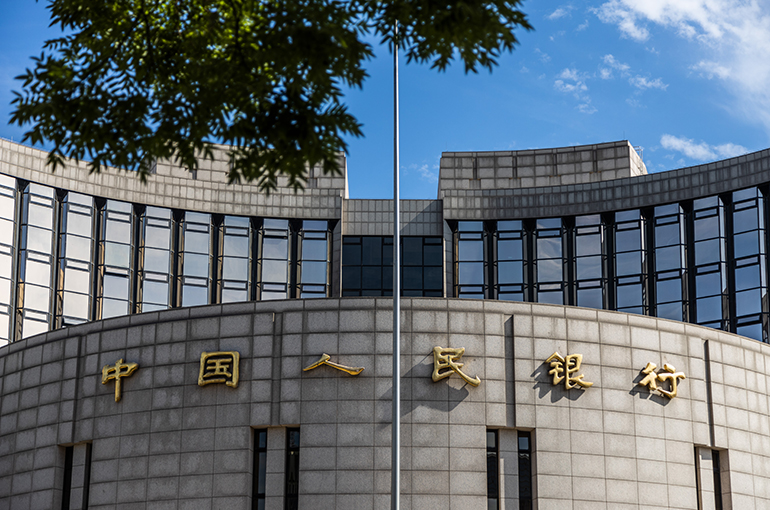
(Yicai) Sept. 21 -- The People's Bank of China injected CNY100 billion (USD14.9 billion) into the market through a 14-day reverse repo at the end of last week. Analysts said the move, combined with multiple seven‑day reverse repo operations and other monetary policy tools, is a pre‑emptive measure by the central bank to address dual liquidity pressures from upcoming holidays and the end of the third quarter, signaling a commitment to maintaining reasonably ample liquidity in the banking system.
The PBOC carried out the CNY100 14-day reverse repurchase operation on Sept. 18. In addition, as the Mid‑Autumn Festival and National Day holiday approach, superimposed with tax payment periods and government bond settlement pressures, the bank steadily scaled up reverse repos, conducting CNY735.3 billion in seven‑day reverse repos and CNY500 billion in outright reverse repos from Sept. 14 to 18.
Seven‑day reverse repo injections were gradually ramped up, with CNY110 billion on Sept. 16, followed by CNY162 billion on Sept. 17 and CNY463.3 billion on Sept. 18. Another CNY32 billion (USD4.8 billion) operation was conducted on Sept. 20. Since 2022, the 14‑day reverse repo tool has usually been launched in mid‑to‑late September, mostly between Sept. 15 and 23.
The CNY100 billion 14‑day reverse repo is designed to cover market funding needs during the Mid‑Autumn Festival, quarter-end, and National Day holiday period, said Liu Yu, chief economist at Industrial Securities. The Sept. 18 resumption broadly aligns with historical seasonal patterns, Liu added.
On scale, the initial CNY100 billion injection is higher than the CNY10 billion to CNY80 billion recorded in the same period from 2022 to 2024, but lower than last year's CNY300 billion, Liu pointed out.
14‑day reverse repos are mainly deployed to adjust liquidity at critical moments, mostly during cross-holiday, cross-quarter, and cross-year windows, according to a report from the fixed income team at Caitong Securities. In non-quarter-end months, such operations are generally triggered by periodic market disturbances, including tax payments and government bond issuances, it noted.
Operation frequency does not equate to liquidity support intensity, the team added. In recent years, while operation frequency has declined, single-transaction scale has expanded, with additional injections usually rolled out later in the month, so the overall policy support should be judged by subsequent liquidity operation rhythms, it stressed.
Overnight reverse repo operations have become a regular monetary tool to regulate liquidity during tax periods and cross-quarter transitions, yet the PBOC has resumed 14‑day reverse repos. According to analysis at Caitong Securities, the move is not only a timely response to mid-week liquidity tightening, but also a proactive measure to stabilize market expectations before funding prices deviate substantially from normal levels, maintaining a supportive policy tone in the market.
Cross-holiday funding demand will likely continue rising from today to Sept. 24, analysts said, adding that coupled with government bond settlement pressures, money market liquidity may see another moderate tightening, though the likelihood of abnormal and sharp seasonal volatility remains low.
Editor: Martin Kadiev