

 PBOC’s Monetary Easing Pause Is Reasonable Amid Plentiful Liquidity, Analysts Say
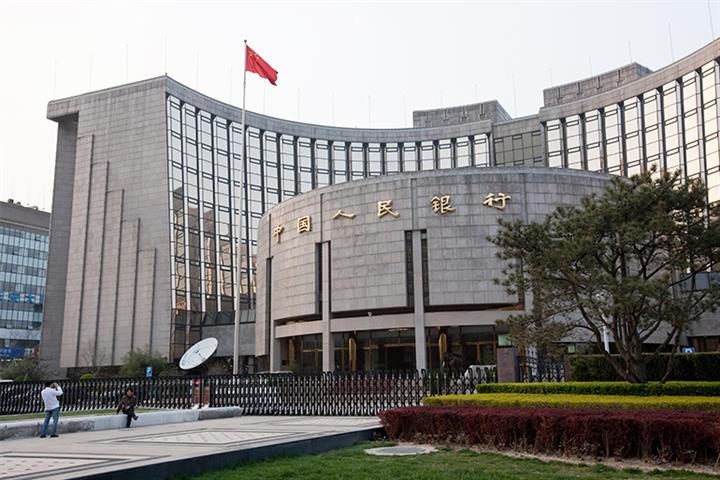
(Yicai Global) Sept. 15 -- The move by the People's Bank of China to pause monetary easing and cut back the medium-term lending facility is reasonable, given the adequate liquidity in the banking system at present, according to analysts.
The PBOC today kept the rate on CNY400 billion (USD57.2 billion) of one-year MLF loans and CNY2 billion (USD285.9 million) of seven-day reverse repos unchanged at 2.75 percent and 2 percent, respectively.
Meanwhile, CNY2 billion of reverse repos and CNY600 billion of MLF loans expired, meaning the bank pulled CNY200 billion of funds from the open market in another scaled-down MLF operation following a CNY200 billion siphoning last month.
A modest contraction is necessary, said Lian Ping, chief economist at Zhixin Investment. Liquidity is abundant in the financial market, especially in the banking system, and given the considerably increased growth of bank deposits last month, the banking system's liquidity is ample at the moment, he noted.
The funding situation will gradually become tighter, said Wen Bin, chief economist at China Minsheng Bank, as the period when the main factors supported a loose funding situation may have ended. But the monetary and financial environment will remain benign as stability returns to the economy, and liquidity will stay at a reasonably ample level, he said.
It is possible that the PBOC might replace part of high-cost MLF loans by cutting the reserve requirement ratio again, given that additional issuance of special bonds may total over CNY500 billion in September and October and CNY2 trillion (USD285.9 billion) of MLF loans will mature in the fourth quarter, Wen said.
Most commercial banks also cut deposit rates today, including Industrial and Commercial Bank of China and China Construction Bank. There were slight changes to rates for easy-access and fixed-term deposits among others, with a larger 15 basis points decline in the rate for three-year deposits.
Lower deposit rates are a natural result of the loan prime rate cuts last month, according to Zhongtai Securities, but it cannot be assumed that there will be another LPR reduction this month even though falling deposit rates do open up room for an adjustment.
Growth in social financing is highly likely to fluctuate in a narrow range later in the year, but it will probably be about 10.3 percent for the whole of 2022, with weakening pressures expected at the year's end, Everbright Securities added. The effect of the pandemic on production and consumption, as well as the property market are the biggest sources of uncertainty, with further LPR cuts expected, the brokerage said.
Editors: Liao Shumin, Tom Litting