

 Android Sector to Face First Major Shakeout in 2027 Amid Financing, Market Headwinds, GGII GM Says
(Yicai) Nov. 4 -- The humanoid robot sector will likely face its first major reorganization next year, constrained by both financing and commercialization progress, according to the general manager of Chinese market research firm Gaogong Industrial Research Institute.
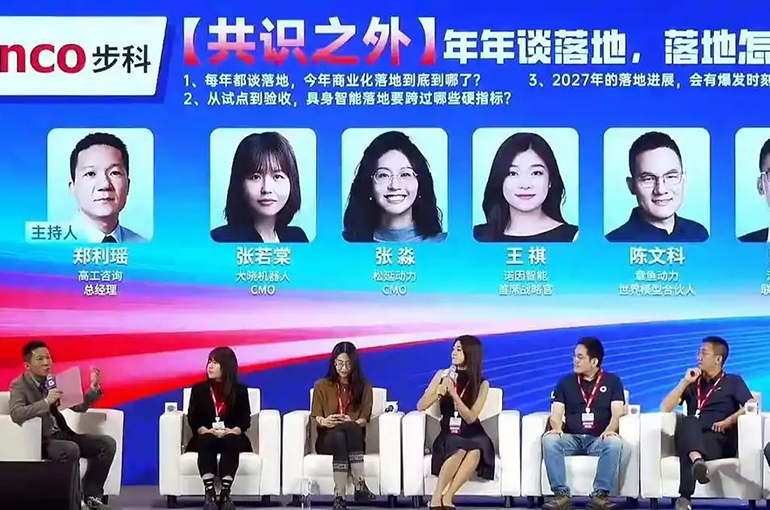
“The humanoid robot industry is shifting from prototype demonstrations to engineered delivery, and from general paradigms to scenario-specific deployment,” Zheng Liyang said at the 2026 GGII Humanoid Robot Annual Conference yesterday.
Commercialization is still hampered by fragmented demand and the absence of killer applications, and industrialization faces pain points including disjointed software and hardware and inconsistent interfaces, he noted. As a result, capital has turned more rational, and the sector is undergoing de-bubbling.
The commercialization of the embodied intelligence industry has reached a new milestone this year, but growth remains below expectations, Zheng pointed out, adding that more than 15 percent of humanoid robot industry players are expected to shut down or be acquired in the next three years.
Global android shipments are projected to reach almost 60,000 units this year, with their market size doubling to about USD2 billion, according to data released by Zheng. Meanwhile, China’s shipments will likely surpass 50,000 units, with a market size of CNY10 billion (USD1.5 billion), missing expectations for over 60,000 units set at the start of the year.
The shortcoming stems from slower-than-expected deployment of humanoid robot products, as multiple constraints are holding back large-scale roll-out of androids, Zheng explained. For instance, the industrial chain is still undergoing vertical integration, with most links lacking sufficient maturity, commercial closed loops for industrial scenarios have not yet been established, and large-scale adoption of dexterous hands awaits further scenario cultivation.
Financing enthusiasm for the humanoid robot sector climbed in the first three quarters of the year but then cooled in the fourth quarter, Zheng said. GGII data shows that the combined financing for Chinese humanoid robot platforms reached CNY81.8 billion in the first three quarters, while financing for component segments, such as dexterous hands, was CNY14.8 billion.
Meanwhile, the price war in the humanoid robot market will continue next year, Zheng forecast. Against this backdrop, the industry is expected to face changes besides merger and acquisition activities, with mid-tier players refocusing on their strongest areas, high-tier players seeking to amplify their existing advantages, and top-tier ones prioritizing seizing leading positions within the industry ecosystem.
Prices of small androids shorter than 1.2 meters will drop to CNY18,000 (USD2,695) per unit next year from CNY20,000 per unit this year, GGII predicted. Meanwhile, those of mid-sized models between 1.2 and 1.6 meters and large ones taller than 1.6 meters will fall to CNY110,000 (USD16,465) from CNY115,000 and to CNY234,000 from CNY268,000, respectively.
Competition will shift toward delivery capability and be centered on robot deployment and real-world applications, according to GGII.
Editors: Tang Shihua, Futura Costaglione